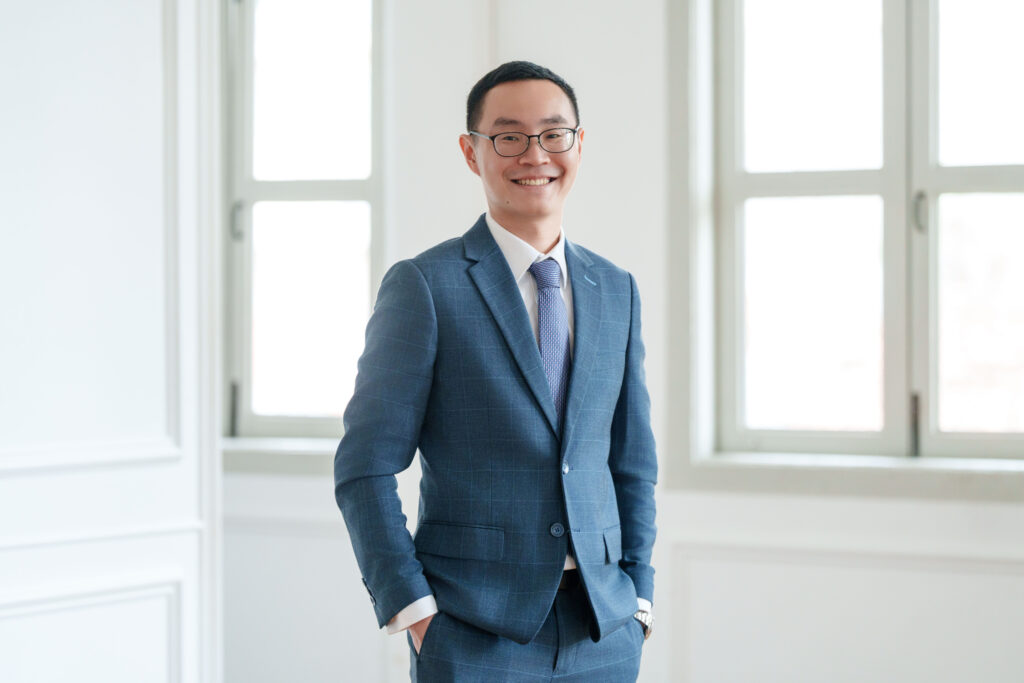
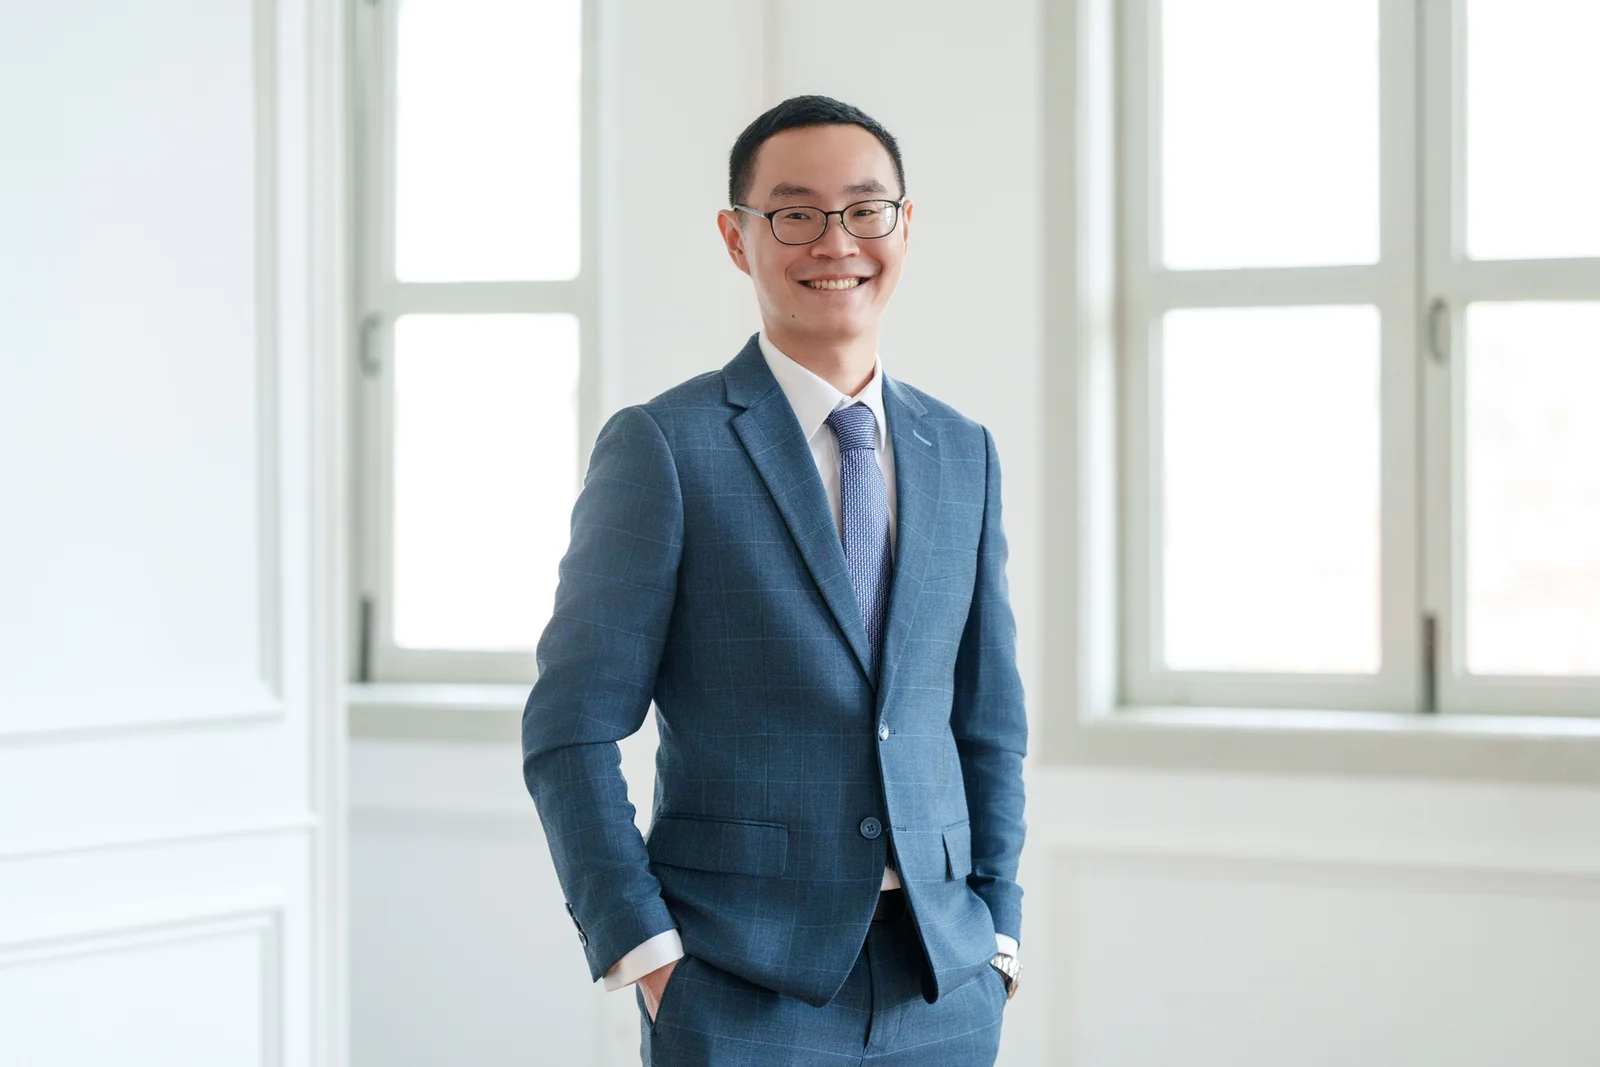
A few years ago, Vincent Chua, a six-year MDRT member, met a couple in their early 40s. The husband held two master's degrees and was, by his own account, not a believer in insurance. His coverage stopped at a basic health and medical plan, nothing beyond the minimum. His wife sat on the opposite end of the spectrum, a firm believer in the value of insurance and eager for the family to be better protected. The imbalance between the two was the conversation's real starting point before any thoughts of what products either of them might eventually buy.
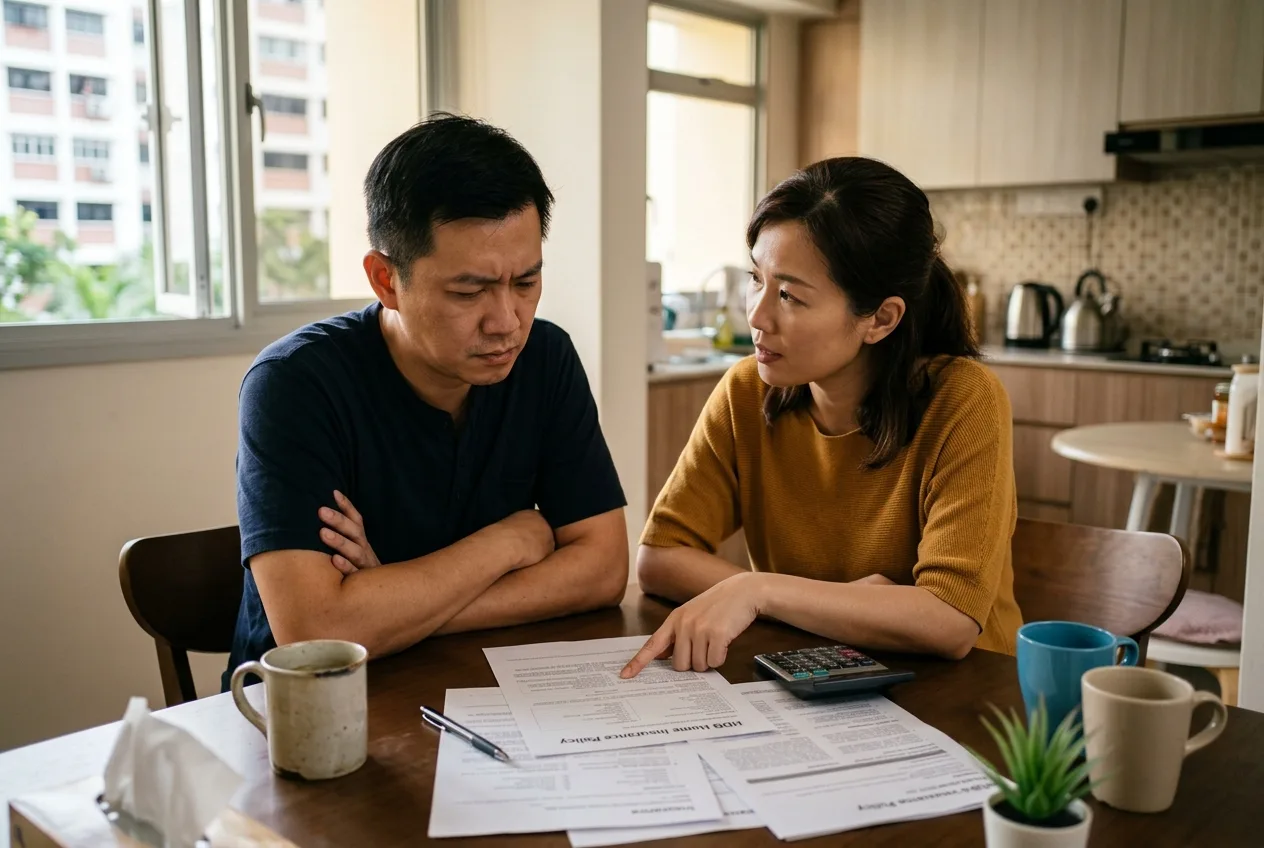
That instinct to understand the person before proposing anything has shaped how Chua runs his practice. Today he serves more than 270 active clients, with a focus on retirement planning and investments. Within that broader practice, Chua has developed a particular skill that many younger advisors find daunting: helping clients who have grown wary of insurance, often after a specific past experience, work through that resistance before any product is discussed.
Understanding the mindset before proposing the solution
When Chua met the couple, he knew that approaching the husband directly as a financial advisor would likely be met with immediate resistance. “If I approach him right now, knowing that I am a financial advisor, for sure the first thing on his mind is, ‘don't waste my time,’” Chua shares. Instead of pushing forward with a pitch, his first task was to understand why the husband had settled so firmly into his position.
“A person is usually consistent. Either you believe in insurance, or you don't. You can't be halfway there, believing in part of it and not the rest.”
That consistency told Chua there was a specific root cause behind the husband's skepticism, and finding it mattered more than any product conversation that might follow. He eventually discovered that the husband's distrust towards insurance stemmed from past experiences with friends who had sold him insurance, only to leave the industry shortly afterwards.
This principle extends beyond any single client. “Regardless of whether the client is a senior or a young adult, it is important to understand the client's mindset because we need to understand their main concern before proposing any product,” Chua shares. He positions himself as an advisor trying to solve a client's needs without pushing a sale. “If I were to lead with product and coverage discussions first, the client may feel that you are trying to sell more than solving their problems.”
Why clients come to believe insurance is a scam
In Chua's experience, the word “scam” almost always traces back to a specific, unresolved experience rather than a rejection of insurance as a concept.
Three roots of skepticism
The friend who left
Maybe they bought insurance from a friend and then the friend left the industry. They felt cheated in a way, because they were there to support the friend who then left.
The policy that never kept up
Older critical illness plans in Singapore often covered only a narrow set of advanced-stage conditions, sometimes as few as 15 to 20. Years later, an early-stage diagnosis falls outside what the policy actually covers, and the blame lands on the advisor.
The excess nobody explained
Deductibles, known locally as excess, catch many clients by surprise. If the medical bill is S$3,000, the first 3,000 is borne by the client. Even with an active policy, a smaller bill can be paid entirely out of pocket.
“From a client's perspective, they think, I've been paying the insurance advisor but now you tell me I can't claim. Then why should I continue the insurance?”
Underneath all these specific grievances, Chua points to something more fundamental about how insurance works. “No one buys insurance thinking, I must claim today, so I can maximize the benefit of it,” he says. “Majority of us, if we buy a critical illness plan or a medical plan, we don't have the intention of wanting to go to the hospital.” Insurance is bought precisely so that it never needs to be used, a concept Chua believes deserves as much airtime as any product feature.
“Given that it's a counterintuitive kind of product, we are buying for peace of mind. I think that part of the mindset is something we need to tackle as well.”
This reframe becomes especially important for older clients. Chua notes that securing insurance later in life, in someone's 60s for instance, tends to be significantly more expensive and the value proposition can feel harder to justify.
A daughter's quiet concern, a mother's protection
That reluctance played out in another case from Chua's practice. Many Asian parents are hesitant to let their children pay for their insurance, worried about being seen as a burden. Both parents initially felt the same way.
Chua's role was to help the couple see that avoiding insurance would not remove risk from the family; all it did was shift a potentially larger burden onto their children later. “I believe most people want the best for their family,” Chua shares. “The perspective then is to reframe what they are doing now versus if they were to change their mindset.”
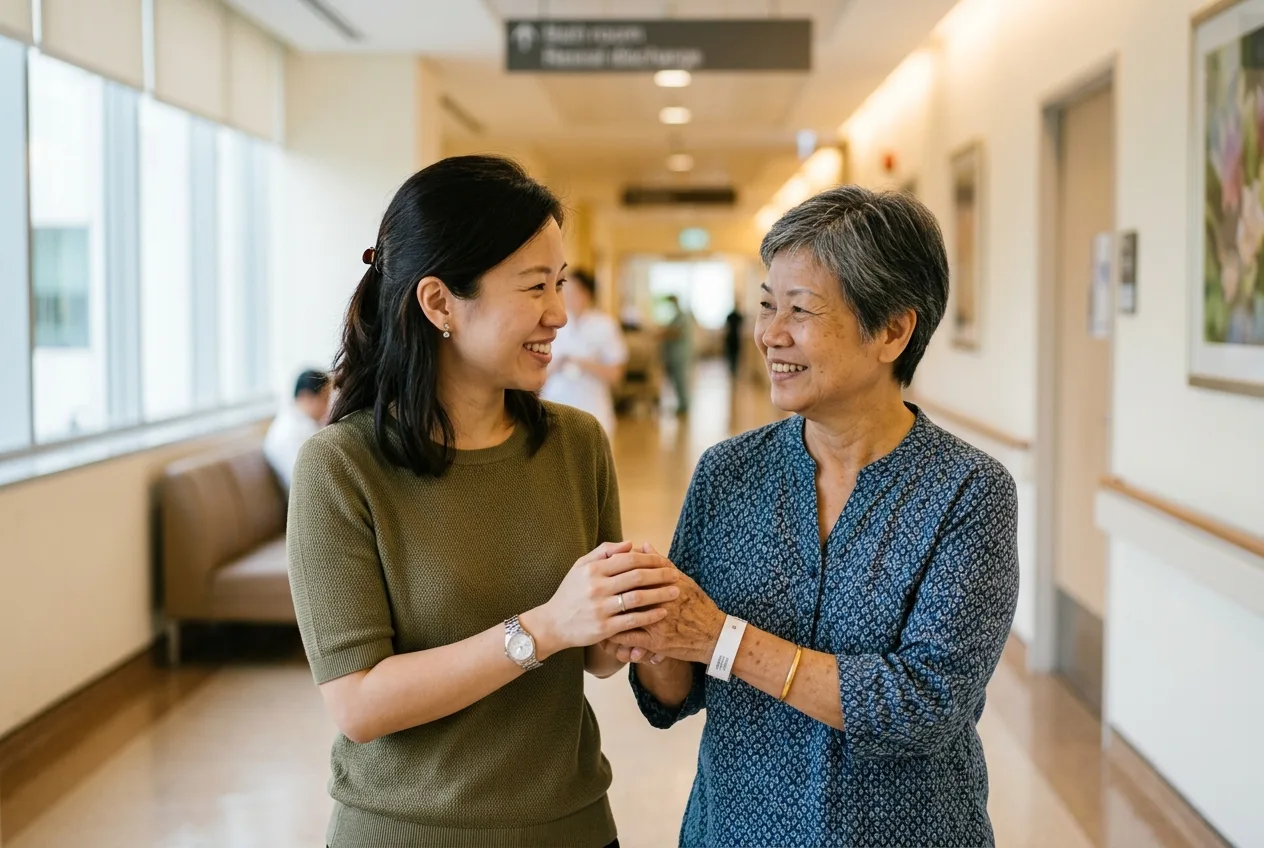
The parents eventually agreed and their daughter took on the premiums. A few years later, the mother was diagnosed with early-stage breast cancer. Because coverage was already in place, she was able to file a claim, and her daughter was able to bring her to a private hospital for a second opinion, while relying on government hospital coverage under the existing plan for her primary treatment. “They were glad that they took up the proposal back then,” Chua shares.
Practical advice for advisors working with skeptical seniors
For younger advisors navigating similar resistance, Chua's advice starts with empathy rather than technique.
“Have empathy and stand in the shoes of the clients. Ask questions and elicit responses more than trying to convince.”
He is also candid that progress with skeptical clients rarely happens quickly. Gaining their trust takes patience and a willingness to move step by step, allowing a client to gradually adapt until ready. Some clients open up to one form of financial planning, such as investments, before they are ready to revisit insurance. Chua treats that sequence as a sign of growing confidence rather than a detour.
Vincent's playbook
- Find the root of the skepticism first. Only then decide what kind of coverage, if any, genuinely makes sense for that person's stage of life.
- Lead with questions, not products. Elicit responses more than you try to convince.
- Move step by step. Let a client start where they are comfortable, even if that is investments before insurance.
- Address budget honestly, and involve family members where appropriate for the extra support a client needs to move forward.
- Reframe the purpose: insurance is bought for peace of mind, so that it never needs to be used.
Budget concerns remain one of the most persistent obstacles he encounters, and involving family members, where appropriate, often provides the additional support a client needs to move forward. Above all, Chua emphasises returning to the same starting point in every difficult conversation: identify the root of the skepticism first and only then decide what kind of coverage, if any, genuinely makes sense for that person's stage of life.
Article text and photography © MDRT, reproduced on this page for Vincent Chua's clients. This is general information and not personalised financial advice. Affinity Group is a group of Financial Adviser Representatives representing Infinity Financial Advisory Pte Ltd.