Business guide · Singapore

Employee benefitsfor Singapore businesses.

Attracting and keeping good people in Singapore's tight labour market depends heavily on benefits. A well-designed group insurance programme protects your staff, satisfies Employment Act and work-pass obligations, and often costs less than you expect. This guide explains what a modern benefits package includes and how Affinity's corporate specialists build and manage one.

Read the guide

Updated 2026-06-20 · Reviewed by Affinity Group advisors

A Singapore SME team protected by an employee benefits plan

Top EB & GI Advisor

Infinity FA's top Employee Benefits & General Insurance advisor, 2021–2025, leads our corporate practice

End-to-end

Design, placement, enrolment, claims support and annual renewal review

SMEs to corporates

Programmes sized for teams of five to several hundred

Quick answer

Employee benefits for Singapore businesses typically include group hospitalisation, term life, outpatient and dental cover, plus keyman and business protection. A well-designed plan helps attract and retain staff, meets Employment Act and work-pass obligations, and often costs less than expected. Affinity's corporate specialists design and manage the programme for you.

What a Singapore employee benefits package includes

  • Group hospitalisation and surgical (GHS) with optional outpatient GP and specialist cover.
  • Group term life and group personal accident cover.
  • Group critical illness and disability income.
  • Dental and wellness benefits.
  • Work Injury Compensation Act (WICA) insurance and mandatory medical cover for work permit and S Pass holders.
  • Flexible benefits and portable medical benefits for tax-efficient design.

Why benefits matter for SMEs

Beyond compliance, benefits shape retention and productivity. Employees with good medical cover take less unpaid leave and worry less; candidates compare benefits across offers. Group cover also lets employees with pre-existing conditions obtain protection they could not buy individually. For owners, the cost is tax-deductible and can be tuned by tier, ward class and co-payment to fit the budget.

Protecting the business itself

Keyman insurance replaces lost revenue if a founder or critical employee dies or becomes disabled. Buy-sell funding lets surviving partners buy out a deceased partner's share without draining the company. Business loan protection keeps personal guarantees from landing on a family. These sit alongside general insurance, property, public liability, professional indemnity, cyber, to cover the risks that could actually stop your operations.

How Affinity serves businesses

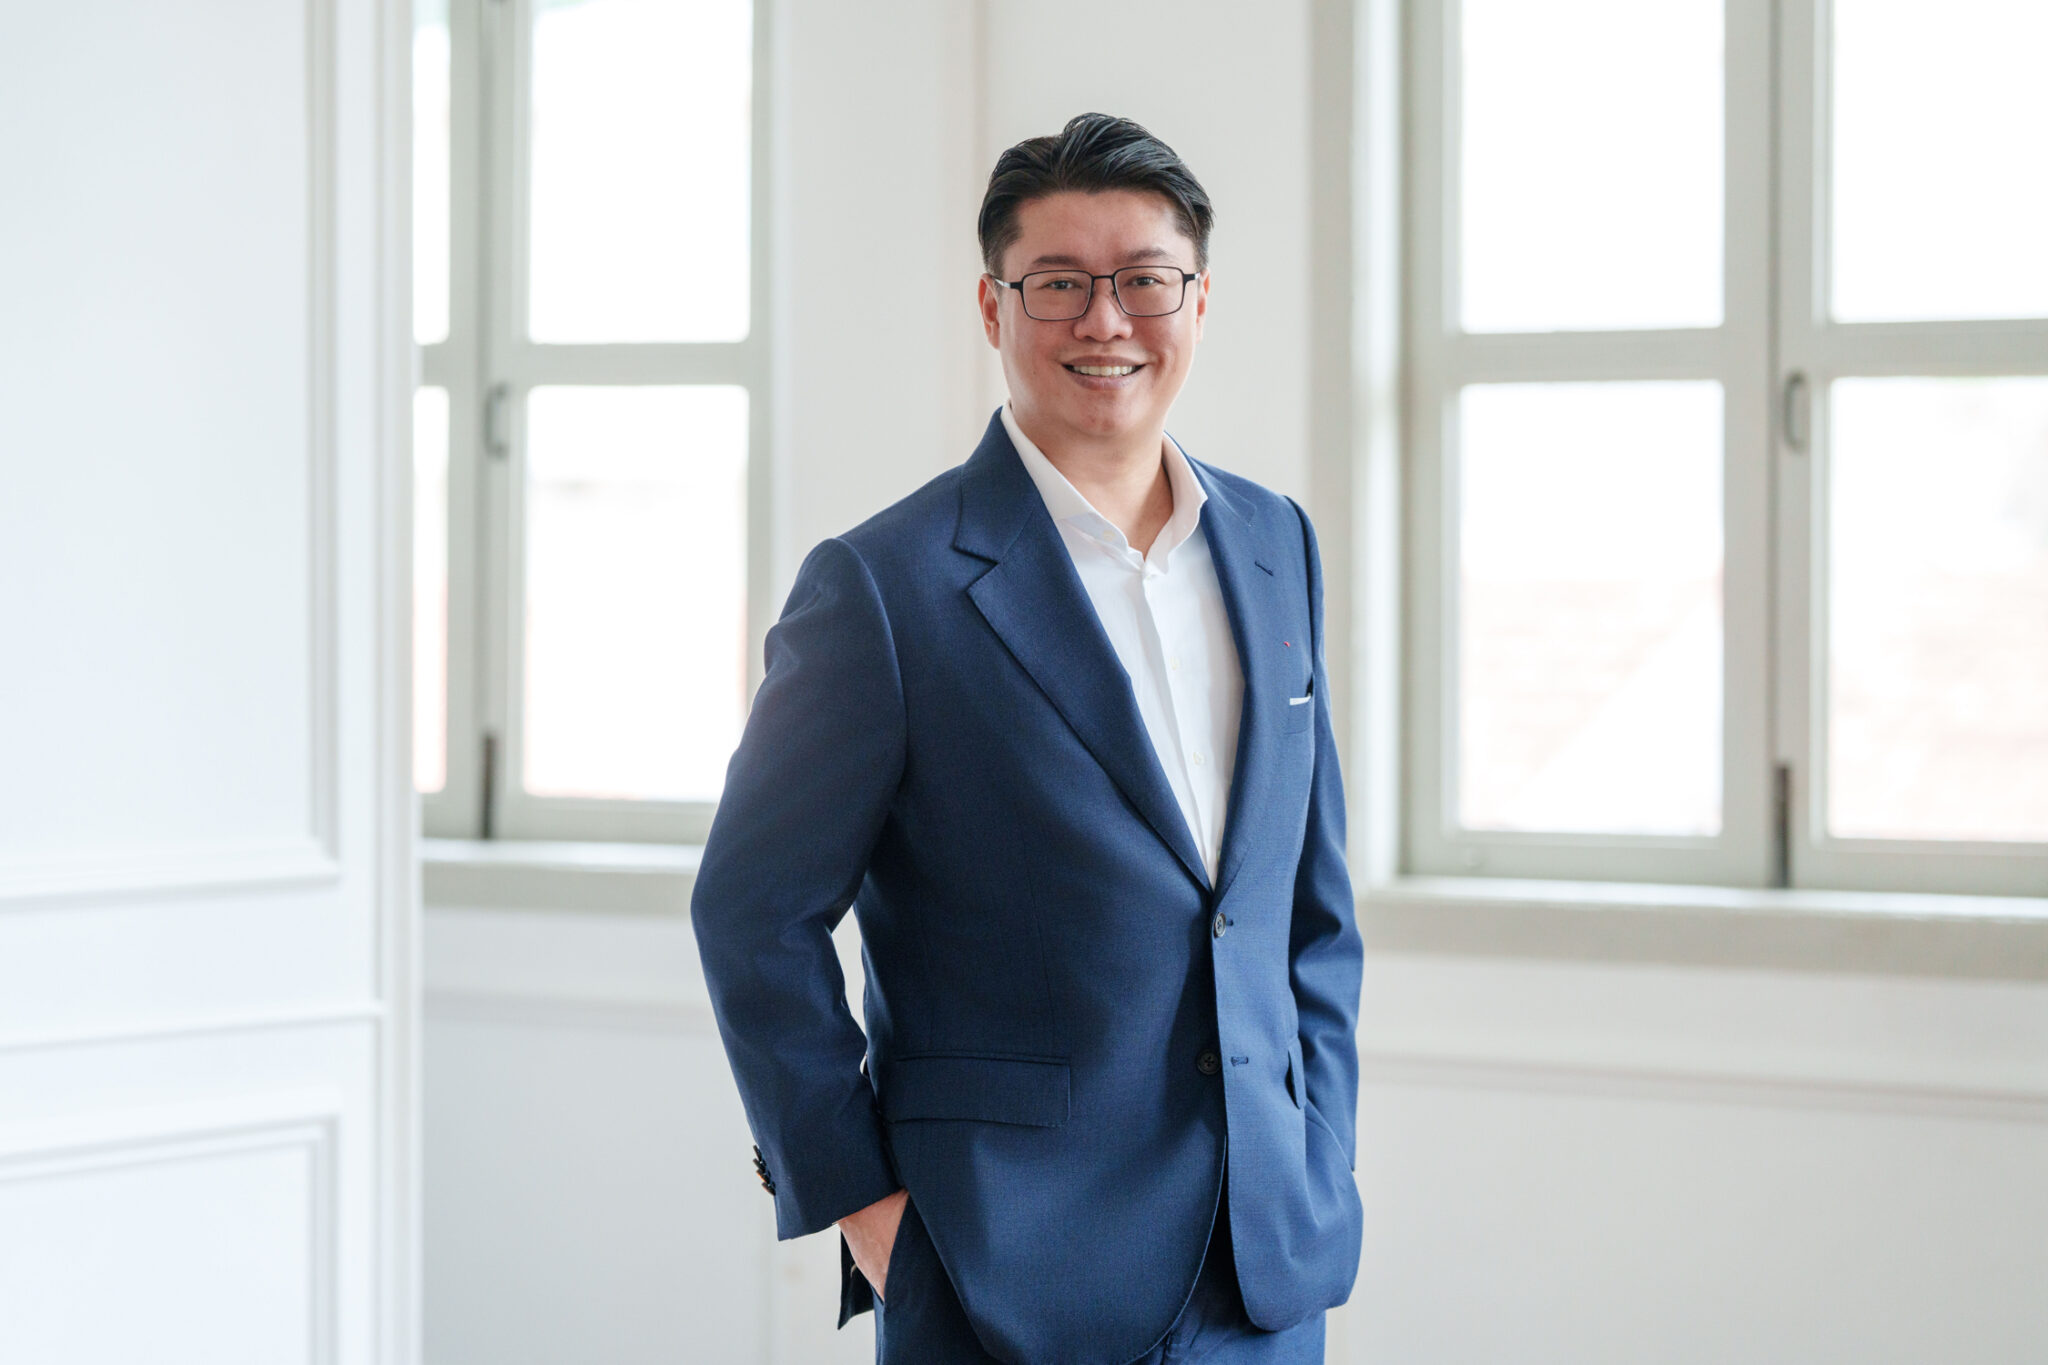
Affinity's corporate practice is led by Ng Jian Da, Infinity Financial Advisory's Top Employee Benefits & General Insurance Advisor for five consecutive years, and supported by advisors who specialise in EB, keyman and business protection. Because we represent a licensed FA firm, we compare group plans across insurers, negotiate renewals, manage enrolment and stand beside HR at claim time. We also advise on business valuation, cash-flow and debt structuring and succession so the company's finances are protected end to end.
How we work

How we build your benefits programme

  1. 01

    Brief

    Understand headcount, demographics, budget and what you want benefits to achieve.

  2. 02

    Benchmark

    Compare your current programme and competitors' packages.

  3. 03

    Design & quote

    Structure tiers and obtain quotes across insurers.

  4. 04

    Launch

    Enrolment, employee briefings and HR documentation.

  5. 05

    Manage

    Claims support, mid-year changes and renewal negotiations every year.

FAQ

Questions we hear most often.

How much does group insurance cost for a small company in Singapore?+

Costs depend on headcount, age profile, ward class and benefit tiers. Basic group hospitalisation for a small team can start from a modest amount per employee per year; we will benchmark options across insurers for your budget.

Is medical insurance mandatory for employees in Singapore?+

Employers must provide medical insurance meeting MOM's minimum coverage for Work Permit and S Pass holders, and WICA insurance for eligible employees. Cover for other staff is voluntary but expected in most industries.

Can employees with pre-existing conditions be covered?+

Group plans typically cover pre-existing conditions for eligible employees, subject to plan terms, a key advantage over individual insurance.

What is keyman insurance?+

Keyman insurance is owned by the company on the life of a key person, paying the business a lump sum on death or disability so it can recover, recruit and reassure lenders and clients.

Do you help with renewals and claims?+

Yes. We manage the programme year-round, including claims escalation, mid-year headcount changes and annual renewal negotiation.

Start a conversation

Good advice begins with someone who listens.

A relaxed, no-obligation first conversation with an Affinity advisor. No products, just understanding.

All services

Keep reading

This guide is general information for Singapore residents and is not personalised financial advice. Speak with a licensed Affinity advisor before making decisions. Affinity Group is a group of Financial Adviser Representatives representing Infinity Financial Advisory Pte Ltd. This advertisement has not been reviewed by the Monetary Authority of Singapore.

Financial planners in Singapore
Financial advisory in Singapore
Retirement planning
Legacy & estate planning
Insurance planning
Investment planning
CPF planning
Employee benefits for SMEs
Financial advisor careers
How to become a financial advisor
Financial planners in Singapore
Financial advisory in Singapore
Retirement planning
Legacy & estate planning
Insurance planning
Investment planning
CPF planning
Employee benefits for SMEs
Financial advisor careers
How to become a financial advisor