Planning guide · Singapore

Investment planningin Singapore.

Investing well is less about picking winners and more about matching a diversified portfolio to clear goals, a realistic time horizon and a risk level you can live with. This guide covers the main investment avenues available to Singapore residents and how Affinity advisors plan and review portfolios.

Read the guide

Updated 2026-06-20 · Reviewed by Affinity Group advisors

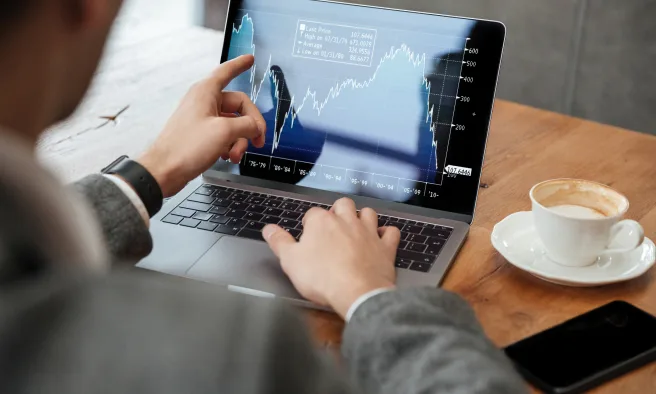
An Affinity advisor reviewing an investment portfolio with a client

Goals-based

Every portfolio is tied to a purpose and a timeline

Diversified

Across asset classes, regions and providers

Reviewed

Regular rebalancing and reviews, not market-timing

Quick answer

Investment planning in Singapore is about matching a diversified portfolio to your goals, time horizon and risk tolerance, not picking winners. Options include unit trusts, ETFs, ILPs, the CPF Investment Scheme and SRS. Affinity advisors build and regularly review goals-based portfolios so your money stays aligned with your plans.

Principles before products

Successful investment plans start with three questions: what is the money for, when will you need it, and how much volatility can you tolerate along the way? A child's university fund due in five years and a retirement pot needed in thirty call for very different portfolios. Only once these are clear should specific funds or products be discussed.

Investment avenues for Singapore residents

  • Unit trusts: professionally managed, diversified funds across equities, bonds and multi-asset strategies.
  • Investment-linked policies (ILPs): combine investment with insurance; suitable in some situations, to be understood carefully.
  • CPF Investment Scheme (CPFIS): investing Ordinary and Special Account savings above the required floors.
  • SRS investing: putting tax-deductible SRS contributions to work rather than leaving them in cash.
  • Regular savings plans: dollar-cost averaging that builds discipline and smooths entry prices.

Understanding risk, fees and time horizon

Every investment carries risk, and the potential for higher returns comes with larger swings. Fees compound over time, so understanding total costs matters. Diversification across asset classes and regions, a long enough horizon and disciplined rebalancing are the most reliable ways to manage risk. Your advisor should be able to explain each of these plainly and show how a portfolio behaved in past downturns.

How Affinity plans investments

Affinity advisors construct portfolios from the range of funds available through Infinity Financial Advisory's platforms, aligned to a documented risk profile and goal. We coordinate investments with CPF, SRS, protection and estate planning so the whole plan works together, and we review portfolios regularly, rebalancing to targets rather than reacting to headlines. Past performance is never a guarantee of future results, and every recommendation is explained before you commit.
How we work

Our investment planning process

  1. 01

    Goals

    Define what each pot of money is for and when it is needed.

  2. 02

    Risk profile

    A documented assessment of risk tolerance and capacity.

  3. 03

    Allocation

    Asset allocation across cash, bonds, equities and alternatives for each goal.

  4. 04

    Implementation

    Select suitable funds and platforms; set up regular contributions.

  5. 05

    Review

    Periodic rebalancing and reviews as goals and markets move.

FAQ

Questions we hear most often.

What is the minimum amount to start investing with an advisor?+

Regular savings plans can start from a few hundred dollars a month. The important thing is to begin with a clear goal and a suitable portfolio, not the size of the first contribution.

Are ILPs a good investment?+

ILPs suit some people and not others. They combine investment with insurance and have their own cost structure. Your advisor should explain the charges, alternatives and whether an ILP genuinely fits your goals before recommending one.

Should I invest my CPF?+

CPF Ordinary and Special Accounts earn interest at rates set by the Government, so investing them only makes sense if you have a long horizon and a portfolio expected to beat that hurdle after fees. It is a decision worth making with a planner.

How often should I review my portfolio?+

At least annually, or when goals change. Frequent trading in response to news usually hurts returns.

Does Affinity provide personalised investment advice?+

Yes, through licensed representatives after understanding your goals and risk profile. Content on this website is general information, not a recommendation.

Start a conversation

Good advice begins with someone who listens.

A relaxed, no-obligation first conversation with an Affinity advisor. No products, just understanding.

All services

Keep reading

This guide is general information for Singapore residents and is not personalised financial advice. Speak with a licensed Affinity advisor before making decisions. Affinity Group is a group of Financial Adviser Representatives representing Infinity Financial Advisory Pte Ltd. This advertisement has not been reviewed by the Monetary Authority of Singapore.

Financial planners in Singapore
Financial advisory in Singapore
Retirement planning
Legacy & estate planning
Insurance planning
Investment planning
CPF planning
Employee benefits for SMEs
Financial advisor careers
How to become a financial advisor
Financial planners in Singapore
Financial advisory in Singapore
Retirement planning
Legacy & estate planning
Insurance planning
Investment planning
CPF planning
Employee benefits for SMEs
Financial advisor careers
How to become a financial advisor